Buying a home starts with knowing your options.
Whether you’re buying your first home, moving into your next one or purchasing an investment property, Rosie can help you understand your financing options before you make your move.
What kind of purchase are you planning?
Different buyers. Different mortgage strategies.
The right mortgage depends on more than the property. Your income, down payment, credit, debts and future plans can all influence the financing strategy.
First-Time Buyer
Get a clearer picture of what you may be able to afford and what documentation may be needed before you start making offers.
Start My Application →Moving to Your Next Home
Review how your current mortgage, home equity, sale proceeds and new financing may work together.
Plan My Next Move →Investment Property
Financing for rental and investment properties can involve different qualification and down-payment requirements.
Explore Financing →Know the numbers before you start house hunting.
A mortgage review can help you understand how your income, debts, down payment and credit profile may affect the amount of financing available.
A bank isn’t the only place to finance a home.
Depending on your financial profile and the property, there may be traditional, alternative or private lending options worth considering.
Traditional Lending
Bank and institutional mortgage products for borrowers who meet conventional income, credit and debt-service requirements.
- Standard income qualification
- Established credit
- Competitive mortgage products
- Purchase financing
Alternative Lending
More flexible mortgage options for borrowers whose income, credit or circumstances do not fit conventional bank guidelines.
- Self-employed borrowers
- Non-traditional income
- Credit challenges
- Flexible qualification approaches
Private Lending
Private financing may provide another route when traditional or alternative lending cannot meet the needs of the transaction.
- Property-focused financing
- Challenged credit situations
- Time-sensitive purchases
- Case-by-case lending
Your first mortgage doesn’t have to feel overwhelming.
Buying your first home can involve a lot of new terminology, paperwork and financial decisions. Rosie can help you understand the mortgage side of the process and what lenders may require.
Self-employed or dealing with credit challenges?
Not every home buyer has a traditional employment history or perfect credit. Alternative and private lenders may evaluate a file differently depending on the complete transaction.
From application to closing.
A little preparation before the offer can make the financing process much easier.
Apply
Tell Rosie about your income, debts, down payment, credit and purchase goals.
Review
Your overall financial picture is reviewed to identify appropriate mortgage paths.
Understand Your Options
Review financing scenarios and understand the lender requirements that may apply.
Make Your Offer
Once you’re ready to purchase, your financing information helps support the next steps.
Finalize Financing
Property details and required documents are submitted to the appropriate lender.
Closing
Rosie helps coordinate mortgage requirements as your transaction moves toward closing.
A declined bank application doesn’t always end the purchase.
Some transactions may be worth reviewing through an alternative or private lender. Property value, down payment, credit, income and the overall transaction can all affect what may be possible.
Private financing may be worth exploring when:
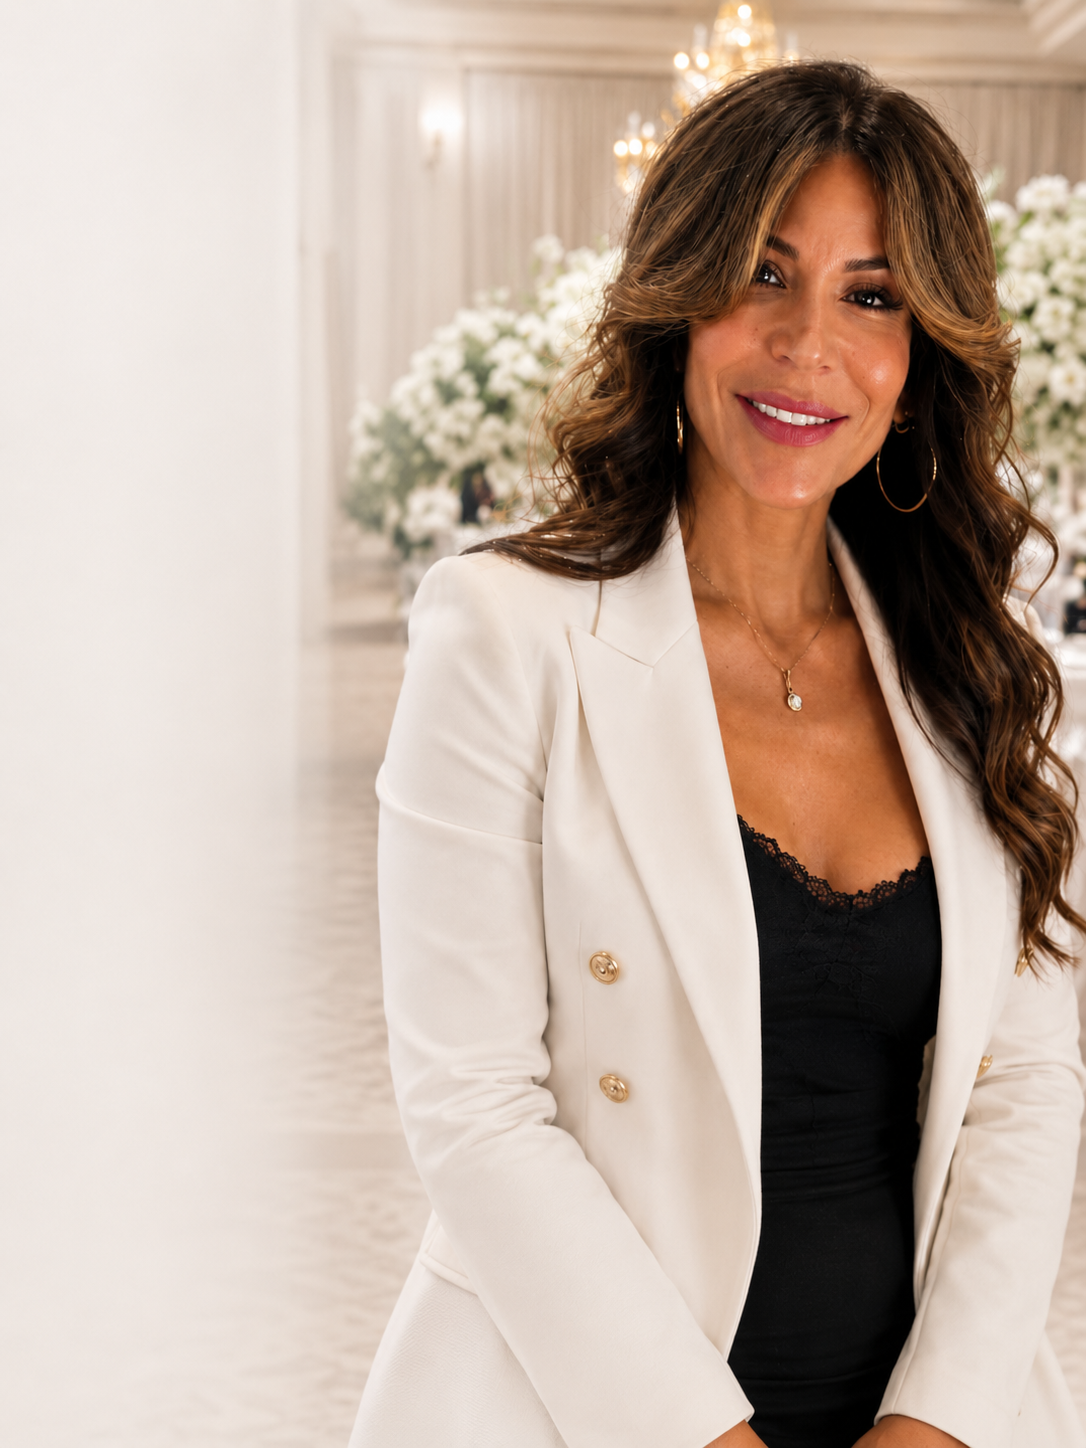
A mortgage conversation before the house hunt.
Rosie Figliomeni helps home buyers understand their mortgage options and prepare for the financing side of purchasing a property.
Whether your situation fits traditional lending or requires a more flexible approach, the goal is to understand the complete picture before deciding on the next step.
Start with your mortgage options.
Tell Rosie about your purchase plans and get started on the financing conversation.